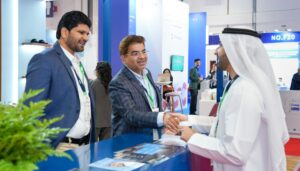
Leapfrogging the legacy core: what we heard at Seamless Middle East 2026
Some of the best conversations at Booth G60 this year...
Updated: October, 2026
Banking as a Service (BaaS), Banking as a Platform (BaaP), and Open Banking use APIs to provide better, faster and more secure financial services for customers. They’re not in competition, but work together to provide better digital banking and online financial experiences.
We’re going to explain what BaaS, BaaP and Open Banking systems are, how they work, and their limitations. We’ll compare them, so you can see what’s included and what’s not, and bring these to life with some real use cases.
Banking as a Service (BaaS) is a solution that enables non-banks to embed finance products into their applications through APIs. Financial products based on BaaS can include accounts, payments, and cards.
You can think about BaaS as a white label service, with a regulated banking institution making its license and infrastructure available to (typically unregulated) third parties.
BaaS makes it simpler, cheaper and easier for third parties, including fintechs, digital banks, and other non-bank businesses to build new products on solid foundations.
Development times of new products can take weeks, with full implementation timeframes as short as a few months. Previously it could have taken a year or more for banks to do this.
Read on: How Can APIs Contribute to Your Business Success?
BaaS is breaking down barriers, making it easier, cheaper and faster for new entrants to offer financial services. Working with a regulated provider means they don’t need to enter into the lengthy and costly process of acquiring a financial services license.
The applications of BaaS are huge. BaaS is popular among early-stage fintech startups, or non-financial businesses that are keen to integrate financial services with minimum development.
The company maintains the customer relationship, with no disruption to the user experience. Behind the scenes, the BaaS platform communicates with the ledger and sends an instruction to the licensed bank provider. The money moves on the payment rail, with the system updated through a webhook.
The simplicity of an API-based BaaS solution enables companies of any size and in any sector to offer loans, lines of credit, or financing inside their own websites or apps. It has the potential to transform financial services.
If you’re a consumer tech company wanting to add financial services to your offer, BaaS is the ready-made solution.
Uber has transformed travel and continues to innovate, using BaaS as the basis for a range of new services. New functionality like Uber’s Cash Wallet, auto top up functionality, and the ability for customers to use multiple payment methods are innovations powered by BaaS systems.
Drivers, too, are benefiting from BaaS, receiving same-day payments from the system and even being able to access cash advances if required. The Uber Pro Card in the UK is an illustration of how Uber is using BaaS to develop localized solutions.
BaaS is enabling Uber to innovate quickly, delivering new solutions for customers and drivers.
BaaS solutions are built on a deep relationship between the customer and the provider, with the potential for vendor lock-in. Because of the deep integration into business delivery, customers must select a BaaS partner they can trust and rely on for the long term.
As with any financial product or solution, there are initial and ongoing regulatory requirements that must be fulfilled that can be resource-intensive and costly.
BaaS is a partnership model and the service must be paid for, which can impact profit. However, the costs and risks must be weighed against the benefits – including the speed to innovate, simplicity of integration, and license requirements.
The BaaS solutions marketplace is saturated, and potential buyers must choose wisely to ensure the provider can deliver the quality, interoperability, and scalability required.
So, what should you look for in a BaaS provider?
Implementing a BaaS solution involves more than technical knowledge; you’ll want to work with a partner that understands your organization and has experience with similar deployments.
As we’ve explained above, BaaS solutions involve two partners (the provider and the customer) effectively integrating their businesses together.
A Banking as a Service solution has four core infrastructure layers that work together:
Banking as a Platform (BaaP) describes the process of a bank using APIs to open up its infrastructure to partners, including fintechs, third-party developers and other service providers.
Banking as a Platform is the inverse of Banking as a Service, and involves the bank integrating third party services into its own system using APIs. This enables the bank to rapidly grow, offering new services or expanding into new markets. Services are built in the cloud and operate on open architectures, giving users a seamless experience.
Crucially, the bank can achieve all this while still “owning” the customer relationship.
As a result, banks can innovate faster than ever before. As well as accelerating expansion, banks can become faster to react to changes in consumer behavior and emerging new trends.
In an age of rapid innovation and the emergence of neobanks, traditional incumbents have been affected by inertia. BaaP can help them break free, enabling them to be more agile, developing new financial products that connect with customers.
By incorporating third parties into their ecosystem, banks can save money on development and support, freeing up internal resources to focus on core activities.
Third-party providers and developers are able to develop new, customer-focused products that can generate a profit. Fintechs are able to piggyback on the existing infrastructure, developing new ideas rapidly and with faster results than in-house teams.
Most importantly, banking customers receive better, more personalized services from their banking providers that can increase loyalty. Using BaaP to remove friction from common banking interactions – like checking a pension account or credit card balance – is a core part of many modern online banking apps.
Banks that rely on legacy infrastructure may not be able to incorporate the APIs required for BaaP. Instead of rapid implementation, banks can find incorporating APIs into existing systems a costly and time consuming process. Even if integration is achieved, banks must ensure that third-party traffic doesn’t interfere with core banking functionality.
BaaP involves banks developing relationships with third parties that can expose the organization to risk. In an increasingly risky environment, banks are understandably worried about increasing their attack surface, limiting the potential for API integrations. This challenge is amplified for banks that work in multiple countries.
More fundamentally, the investment required to enable BaaP is significant. While the customer experience may be improved, it may take years for the bank to recoup its investment.
Starling Bank is a successful example of a modern bank using BaaP to expand its service offer. The online bank has opened up its infrastructure, enabling third-party platforms like accounting provider Xero to automatically sync transactions, saving business owners time.
Personal banking customers can take advantage of the benefits of BaaP, using third-party services like PensionBee’s pension tracker to stay on top of savings.
BaaP is enabling Starling to incorporate new, innovative and genuinely useful new services in its platform, increasing customer satisfaction and powering growth.
A modern, cloud-native core banking platform provides the modularity, scalability, and API-first connectivity required for BaaS and BaaP. There are four elements:
Open banking is a regulatory framework that lets customers securely share their bank data with authorized third parties, or let those parties initiate payments, through APIs.
Like BaaS, open banking uses APIs to communicate with other banks and financial providers, but the purpose is different. BaaS enables firms to offer banking products, while open banking gives access to data.
The shift to open banking has been made possible by positive changes to regulation across the world. For example, changes to PSD2 in Europe are enabling the release and sharing of data by banks in a secure, standardized form.
Open banking provides a seamless, safer, and much simpler experience for customers. Instead of having to switch between platforms and apps, they can switch between providers.
Customers can use new options like “Pay by bank” and be transferred directly to their account. A new generation of apps can use Variable Recurring Payments (VRPs) to access variable amounts of money, accruing them in separate pots. Open banking enables customers to use single apps to see all financial pots, simplifying financial management.
Open banking gives providers with more data, developing more sophisticated and accurate customer profiles. These insights can help to improve the overall customer experience. It also means banks can target customers with relevant products and services, such as loans, with a potentially higher chance of success.
Payment provider Klarna is using open banking solutions to power its rapid growth. At the checkout, customers can select payment by bank and be carried through to their provider, removing the need to manually enter credit card details.
The payment preference is stored, enabling one-click checkout. It’s faster for the customer and better for the business, with 9 million users choosing Klarna every day.
| Feature | Banking as a Service (BaaS) | Banking as a Platform (BaaP) | Open Banking |
| Provider | Licensed banks | Banks who open their APIs to third-parties | Banks and other account providers |
| Users | Fintechs, retailers and non-banks who want to offer financial services | Fintechs and developers who want to build on the bank ecosystem | Regulated third-party providers (TPPs) and customers |
| Use cases | Branded accounts, loans and lending, embedded finance | Partner apps accessible through the banking infrastructure, including budgeting, insurance, and accounting | Account aggregators, budgeting and credit checking apps, account switching and payment initiation |
| Information flow: | Outward: Bank to the Third-Party | Inward: Third-Party to Bank | Data sharing: Bank to an authorized Third-Party |
| What’s shared? | License & infrastructure | Access to infrastructure for development | Data |
| Primary purpose | Creating new, branded financial products | Enhancing the bank’s own products | Sharing data and enabling faster payments |
| Who owns the accounts? | Owned by the brand, issued by the bank | Owned by the bank | Customer’s original bank |
| Regulation required | Banking licenses, KYC/AML compliance | Internal risk & vendor management | Data privacy & consent (e.g., PSD2 / GDPR) |
BaaS, BaaP, and Open Banking aren’t in competition. As we’ve explained, they’re different ways that banks, fintechs, and third parties can collaborate to improve the customer experience.
New technologies and approaches like BaaS, BaaP, and Open Banking are making it easier than ever to innovate in financial services. Organizations and leaders need to understand the potential for new technologies and solutions, and how these can be applied to improve the customer experience.
Start here: A European CIO’s Guide to Progressive Core Modernization.
Whether you’re modernizing your core, launching new products, or exploring what’s next—we’re here to help. Get in touch to see how Tuum can support your vision.